
Top 10 Solana Staking Statistics and Trends in 2026
The table brings together the main benchmarks from our analysis for a quick view of Solana's staking ecosystem as it enters Q4 2026:
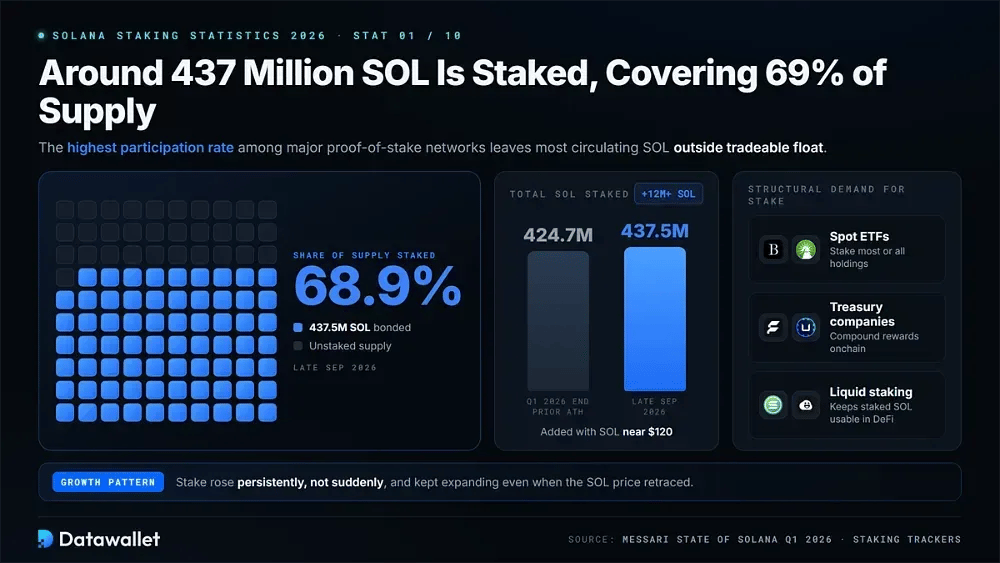
1. Around 437 Million SOL Is Staked, Covering 69% of Supply
Solana's staking base has continued to rise. By late September 2026, roughly 437.5 million SOL is bonded to validators, equivalent to about 68.9% of total supply. That remains the highest participation rate among major proof-of-stake networks and leaves most circulating SOL outside immediately tradeable float.
Growth has been persistent rather than sudden. Messari's State of Solana Q1 2026 report put total stake at an all-time high of 424.7 million SOL at quarter-end. Since then, the network has added more than 12 million SOL despite uneven price action around $120.
Several structural sources of demand have supported that increase. Spot ETFs stake most or all of their holdings, while digital asset treasury companies compound rewards onchain. Liquid staking tokens also allow delegated SOL to remain productive across DeFi, helping stake balances expand even when the SOL price retraces.
2. The Validator Set Thins Toward 700 as Economics Bite
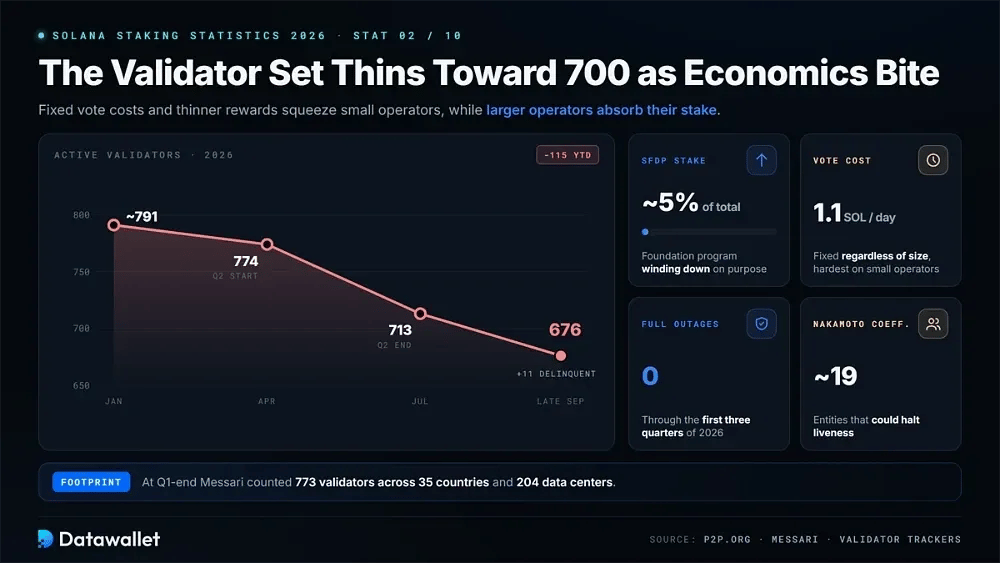
Validator consolidation remained a feature of 2026. P2P.org's institutional staking review shows the active set declining from about 774 to 713 during Q2. By late September, trackers counted 676 active validators plus 11 delinquent ones. Fixed voting costs, combined with lower rewards, continue to pressure the smallest operators.
Key signals across the shrinking validator set:
- Headcount: Active validators dropped from roughly 791 at the start of 2026 to fewer than 720 by mid-year, continuing a multi-year consolidation trend.
- Quality shift: Messari counts 773 validators across 35 countries and 204 data centers at Q1-end, while larger, better-capitalized operators absorbed stake from those leaving the network.
- SFDP wind-down: Solana Foundation Delegation Program stake declined to roughly 5% of the total as the program deliberately pushed validators toward economic self-sufficiency.
- Vote costs: Voting fees remain fixed near 1.1 SOL per day regardless of validator size, making weaker rewards or lower SOL prices especially difficult for smaller operators.
- Reliability record: Solana recorded zero full outages through the first three quarters of 2026, strengthening its institutional case even as the validator set contracted.
- Concentration watch: The Nakamoto coefficient remains near 19, meaning network liveness still depends on a relatively small group of the largest staking entities.
3. Native Solana Staking Yield Sits Near 5.3% to 6.4% APY
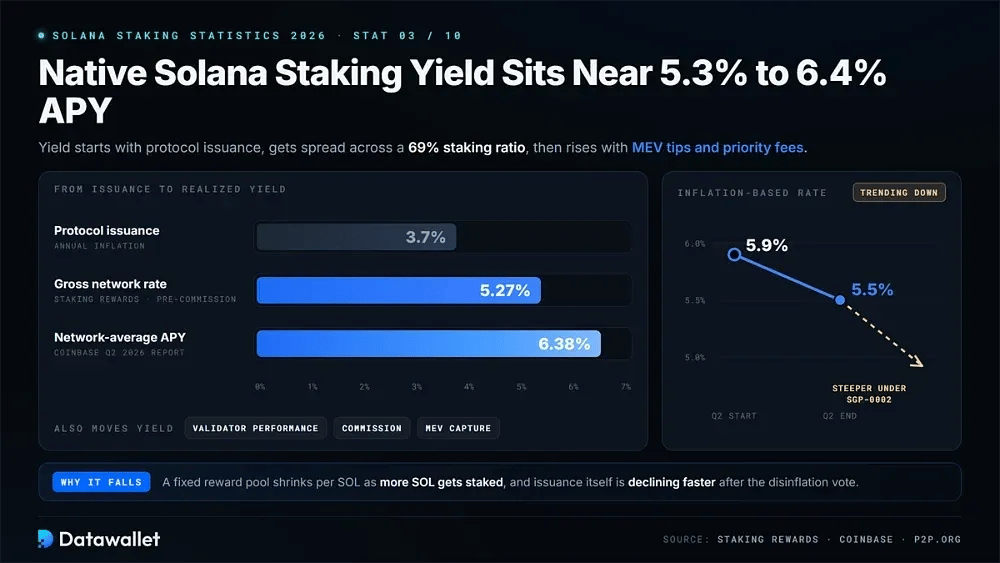
Native yield has declined as issuance has fallen. Staking Rewards benchmarks placed the gross network rate around 5.27% before commission in late September. By comparison, Coinbase's Q2 2026 validator report measured a 6.38% network-average APY after accounting for MEV tips and priority fees.
Protocol issuance is the starting point for realized returns. It is now near 3.7% annually and is scheduled to decline more quickly under the approved disinflation change. The staking ratio also matters because a fixed reward pool produces smaller allocations when more SOL is staked. Validator performance, commission levels, and MEV capture create additional differences between operators.
The direction of travel is more important than any single yield snapshot. P2P.org reports that the network's inflation-based staking rate eased from about 5.9% to 5.5% across Q2 alone. That decline becomes steeper once SGP-0002's accelerated schedule activates on mainnet.
4. Liquid Staking Holds Near 16.6% After Its Record Run
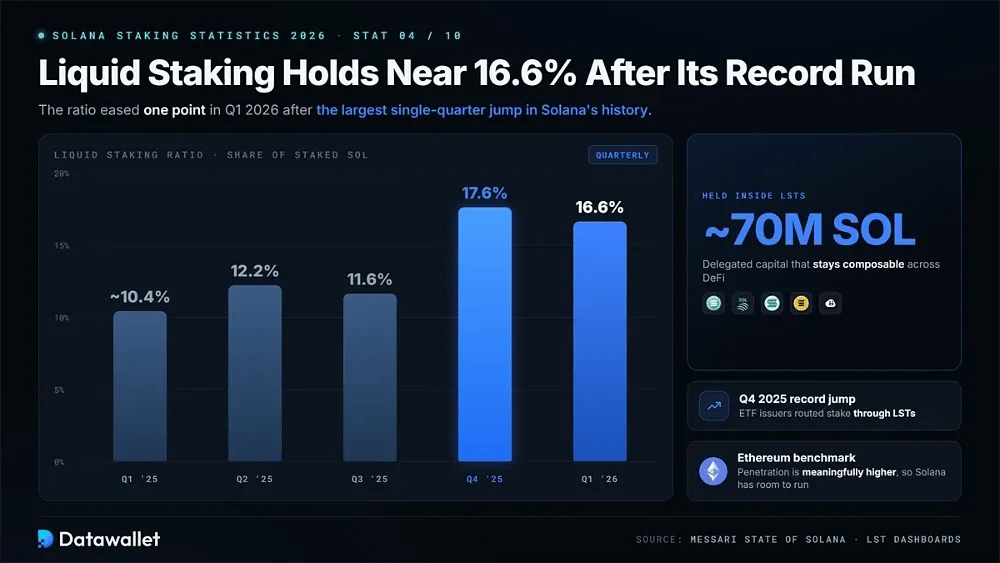
The liquid staking ratio fell from 17.6% to 16.6% quarter-on-quarter in Q1 2026 after the largest single-quarter increase in Solana's history. Even after that pullback, around 70 million SOL remains inside liquid staking tokens, allowing delegated capital to stay composable across DeFi.
How the liquid staking ratio has evolved by quarter:
- Q1 2025: ~10.4% of staked SOL, a mild pullback as native staking expanded faster than LST issuance.
- Q2 2025: 12.2%, representing 16.8% quarterly growth driven by jitoSOL and jupSOL adoption.
- Q3 2025: 11.6%, a modest contraction during the market's September peak and subsequent retrace.
- Q4 2025: 17.6%, the largest quarterly increase on record as ETF issuers routed stake through LSTs.
- Q1 2026: 16.6%, with Sanctum moving ahead of Jito as the largest issuer by market share.
- Ethereum benchmark: Comparable liquid staking penetration on Ethereum remains meaningfully higher, leaving Solana additional room to convert native stake.
5. Sanctum Overtakes Jito as the LST Market Leader
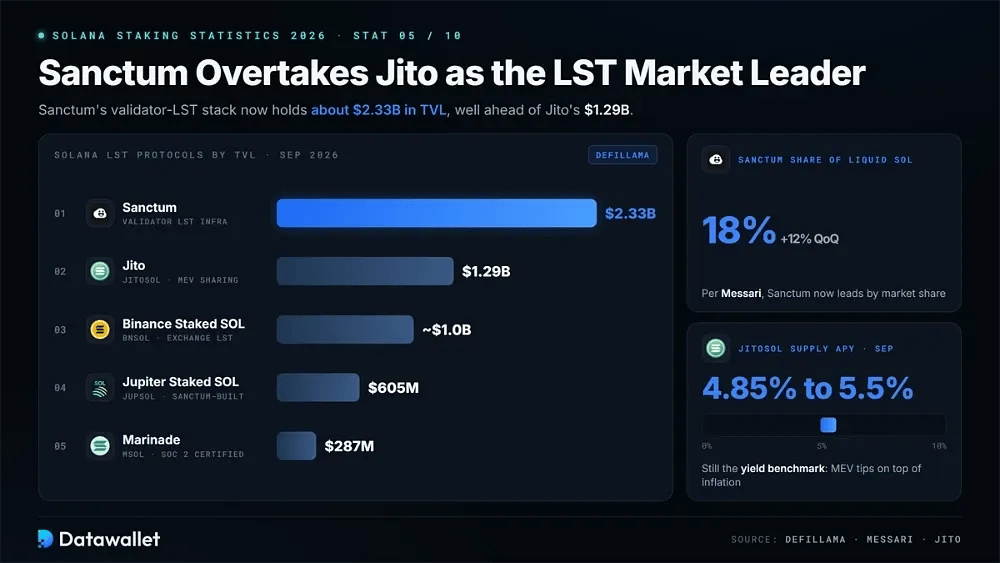
The LST leaderboard changed in 2026. DefiLlama data compiled in late September 2026 puts Sanctum's validator-LST stack at about $2.33 billion in TVL, compared with Jito's $1.29 billion. Messari also documented the shift, reporting that Sanctum's market share rose 12% QoQ to 18% of all liquid staked SOL.
The broader Solana LST map as of September 2026 includes:
- Sanctum: ~$2.33B TVL. Infrastructure for validator-specific LSTs, including ETF and treasury tokens.
- Jito Liquid Staking: ~$1.29B TVL. JitoSOL remains the largest single LST and pioneered MEV reward sharing on Solana.
- Binance Staked SOL: ~$1.0B TVL. bnSOL is an exchange-issued LST supported by deep centralized distribution.
- Jupiter Staked SOL: ~$605M TVL. jupSOL is a Sanctum-built validator token with subsidized commission.
- Marinade: ~$287M TVL. mSOL is the original Solana LST, with SOC 2 certification and institutional products.
JitoSOL still serves as the yield benchmark because of MEV. Its stake pool tracked average supply APY near 4.85% to 5.5% in September, with MEV tips added to base inflation rewards. For a detailed protocol overview, see our Jito and JitoSOL guide, or compare providers in our best Solana staking platforms roundup.
6. US Spot Solana ETFs Approach $1.6 Billion in Cumulative Inflows
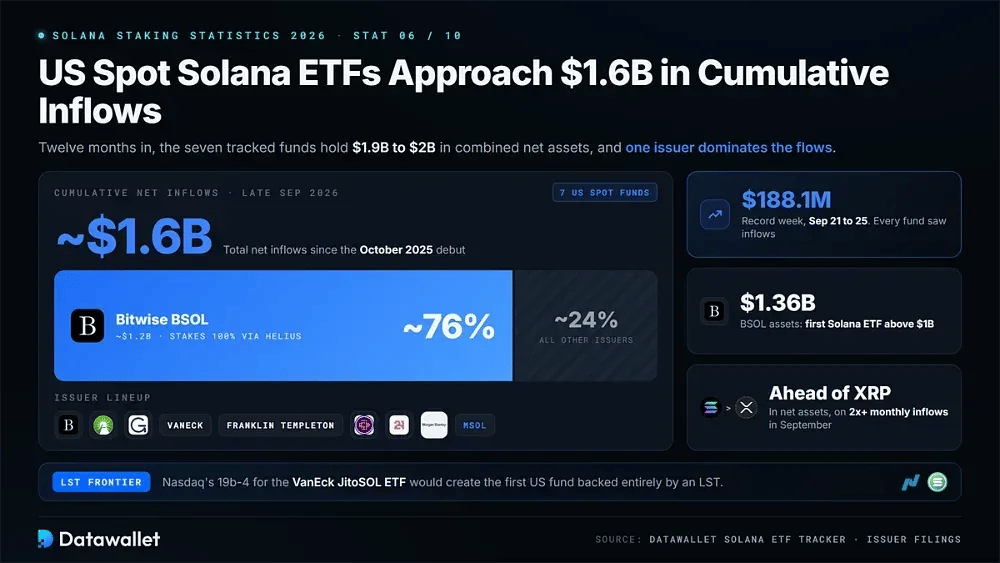
September 2026 brought another acceleration in Solana ETF flows. The seven tracked US spot funds attracted a record $188.1 million during the week of September 21 to 25, their strongest week since launch, and every product recorded positive flows. Daily figures are available on our Solana ETF tracker.
Where the US Solana ETF market stands after twelve months:
- Cumulative inflows: Total net inflows reached roughly $1.6 billion by late September, while combined net assets moved between $1.9 billion and $2 billion.
- Bitwise dominance: BSOL represents about $1.2 billion of cumulative inflows, or roughly 76% of the category, and stakes 100% of its holdings through Helius validators.
- Asset milestone: BSOL surpassed $1.36 billion in assets, becoming the first Solana ETF above $1 billion less than a year after its October 2025 debut.
- Beating XRP: Solana ETFs moved ahead of XRP products in net assets during September, supported by monthly inflows that were more than double their rival's total.
- Issuer depth: Fidelity, Grayscale, VanEck, Franklin Templeton, Canary, 21Shares, and Morgan Stanley's MSOL complete a broader and increasingly competitive issuer lineup.
- LST frontier: Nasdaq's 19b-4 filing for the VanEck JitoSOL ETF would establish the first US fund backed entirely by a liquid staking token.
7. Solana's First Binding Governance Vote Doubles the Disinflation Rate
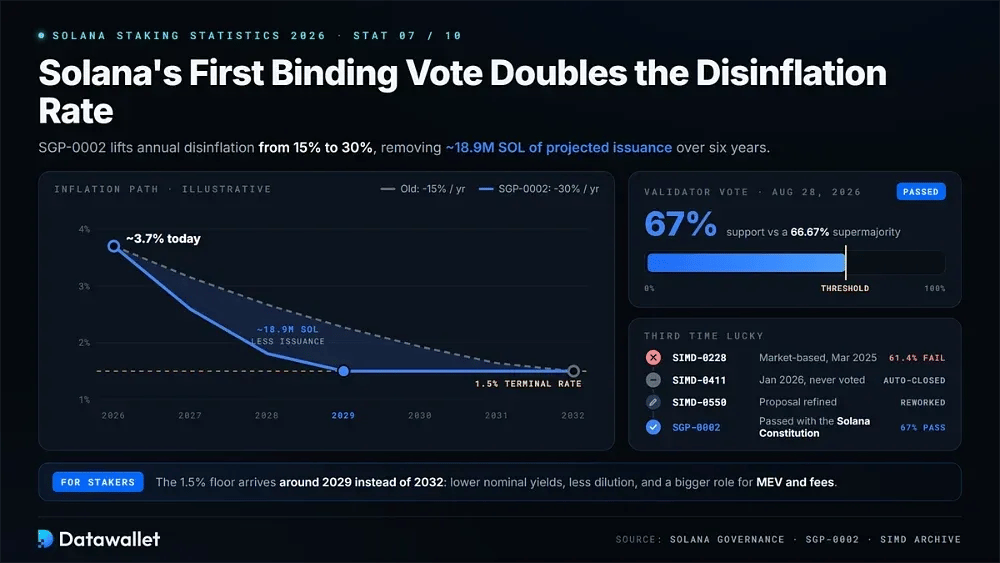
Solana's multi-year inflation debate reached a decision on August 28, 2026. Validators approved SGP-0002, called Double Disinflation, with 67% support, just above the 66.67% supermajority threshold. The measure doubles annual disinflation from 15% to 30% and removes roughly 18.9 million SOL from projected issuance over six years.
Approval came on the third attempt. SIMD-0228's market-based model received 61.4% support and failed in March 2025. SIMD-0411 auto-closed in January 2026 without a vote. The proposal was then refined through SIMD-0550 and resubmitted as SGP-0002 under Solana's formal governance process, passing alongside a ratified Solana Constitution.
What the accelerated schedule means for stakers:
- Faster terminal rate: The 1.5% inflation floor is expected around 2029 rather than 2032, shortening the period of elevated inflation-funded yields.
- Nominal yields fall: Issuance-based rewards decline at roughly twice the previous annual pace, while rewards already earned remain unaffected by the re-anchored formula.
- Real returns improve: Lower dilution affects non-stakers less, while reduced validator sell pressure supports SOL's long-run supply picture.
- MEV weighting grows: With issuance declining, priority fees and MEV tips make up a larger portion of validator revenue, increasing the importance of validator selection.
- Governance precedent: SGP-0002 became Solana's first binding onchain vote and established the process for future monetary and protocol changes.
8. Client Diversity Arrives: Jito Family Falls to 54% of Stake
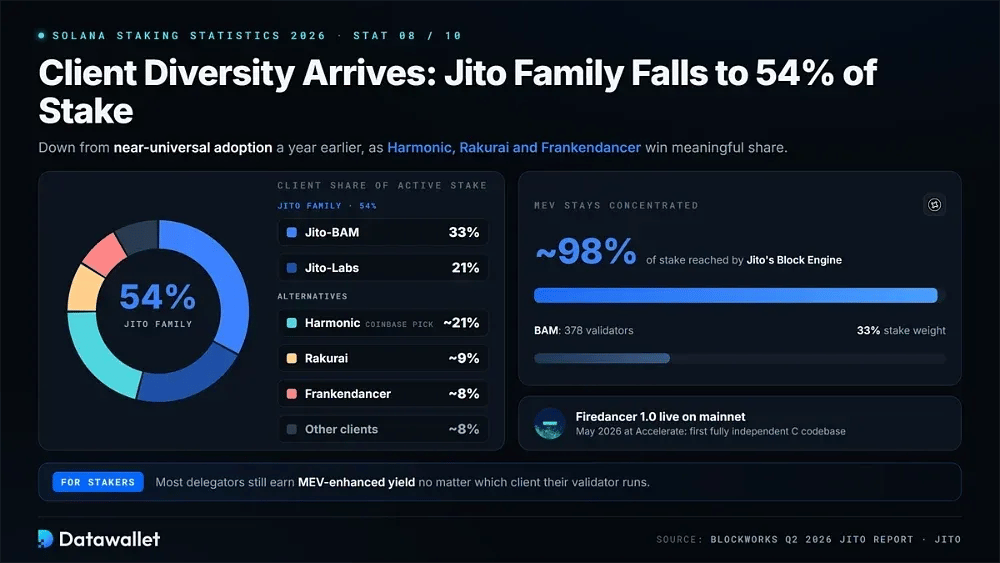
Solana no longer has a client monoculture. Blockworks' Q2 2026 Jito report places the Jito client family at about 54% of active stake. Jito-BAM accounts for 33% and Jito-Labs another 21%, a substantial decline from near-universal adoption one year earlier.
Alternative clients now hold meaningful shares. Harmonic, Coinbase's preferred Foundation-aligned scheduler, represents roughly 21% of stake. Rakurai accounts for about 9%, with Frankendancer near 8%. Firedancer 1.0 went live on mainnet in May 2026 at Solana Accelerate, giving validators a fully independent C-language codebase for the first time. Our Firedancer explainer covers the upgrade in more detail.
MEV distribution remains far more concentrated. Jito's Block Engine still reaches about 98% of total stake, while its Block Assembly Marketplace expanded to 378 validators and 33% of stake weight. As a result, most stakers receive MEV-enhanced yield regardless of the client used by their validator.
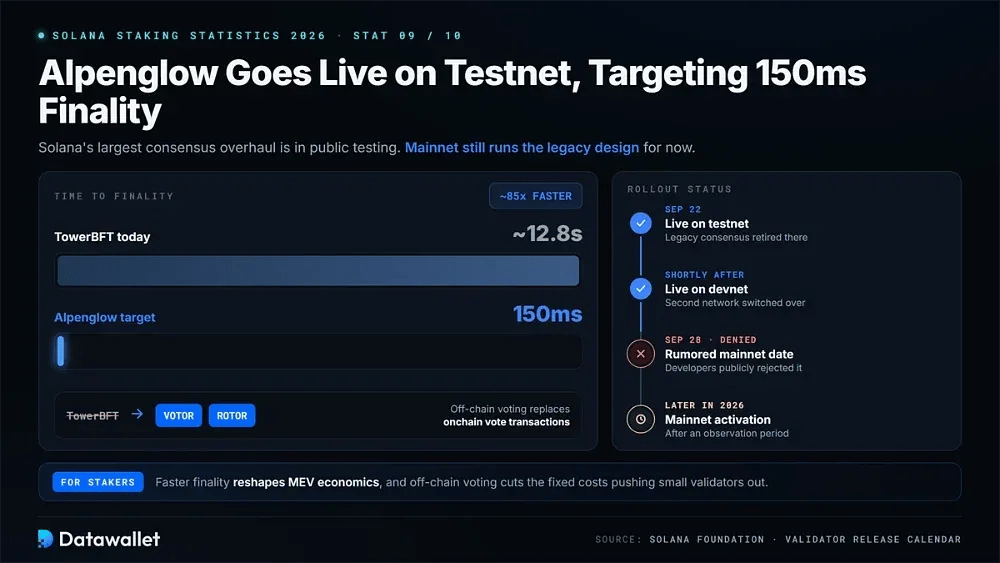
9. Alpenglow Goes Live on Testnet, Targeting 150ms Finality
Solana's largest consensus overhaul has moved into public testing. Alpenglow replaces TowerBFT voting with the Votor and Rotor protocols and activated on testnet on September 22 and devnet shortly after. The legacy consensus system has been retired on those networks, while mainnet continues to use the existing design.
Expectations briefly moved ahead of the actual rollout. A validator release calendar listed September 28 for resumed feature activations, prompting speculation about an imminent mainnet switch. Developers publicly denied the date, and the Solana Foundation reiterated that Alpenglow remains on track for mainnet later in 2026 following an observation period.
The change has direct consequences for stakers. Reducing finality from roughly 12.8 seconds to a targeted 150 milliseconds changes MEV economics. Moving from onchain vote transactions to direct off-chain voting also cuts the fixed voting expenses that have been pushing smaller validators out of the active set.
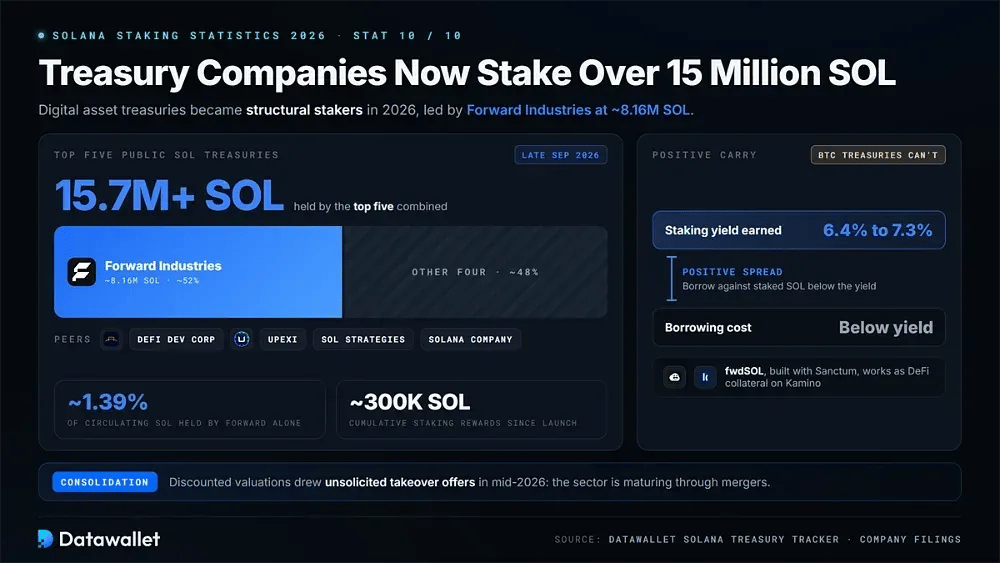
10. Treasury Companies Now Stake Over 15 Million SOL
Digital asset treasury companies became a structural part of Solana staking during 2026. Forward Industries increased its holdings to about 8.16 million SOL by September 21, 2026, and stakes effectively all of it. Meanwhile, the top five public SOL treasuries collectively hold more than 15.7 million SOL. Our Solana treasury tracker follows the full list.
Why DAT staking matters for the network:
- Supply share: Forward alone controls roughly 1.39% of circulating SOL, making it the largest disclosed SOL position among publicly traded companies worldwide.
- Compounding stake: Since launch, the company has generated about 300,000 SOL in cumulative staking rewards, increasing its position without additional capital outflows.
- LST issuance: Forward worked with Sanctum to issue fwdSOL, a treasury-branded liquid staking token that can be used as DeFi collateral on venues including Kamino.
- Positive carry: Treasuries borrow against staked SOL at rates below their 6.4% to 7.3% staking yield, a structure that Bitcoin treasuries cannot use.
- Peer group: DeFi Development Corp, Upexi, SOL Strategies, and the Solana Company follow similar accumulate-and-stake models at smaller scale.
- Consolidation phase: Discounted DAT valuations led to unsolicited acquisition offers in mid-2026, suggesting the sector is maturing through mergers rather than additional entrants.
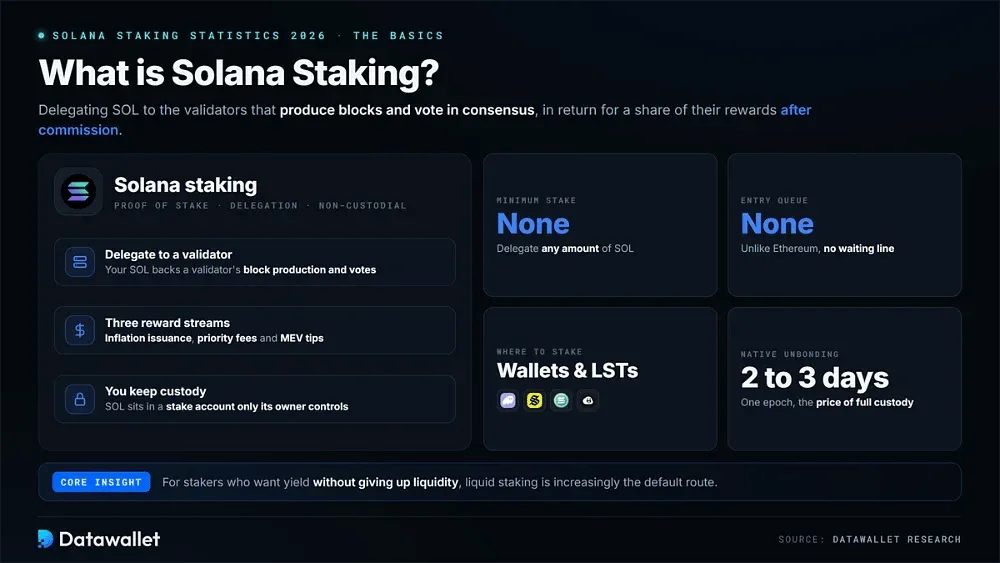
What is Solana Staking?
Solana staking means delegating SOL to validators responsible for producing blocks and voting in consensus. In return, validators receive inflation issuance, transaction priority fees, and MEV tips. Those rewards are passed to delegators after commission. The arrangement is non-custodial because the SOL remains inside a stake account controlled only by its owner.
Unlike Ethereum, Solana imposes no minimum stake and has no entry queue. Users can delegate any amount of SOL to a validator through wallets such as Phantom or Solflare, a Solana staking platform, or an LST protocol. Our best Solana wallets guide compares the available interfaces.
Most stakers currently choose between three routes. Native delegation provides the greatest custody control but requires a two-to-three-day unbonding period. Liquid staking offers immediate exits while keeping capital usable in DeFi. Regulated wrappers such as staking ETFs provide brokerage-account exposure. For users who want yield without giving up liquidity, liquid staking is increasingly the default.
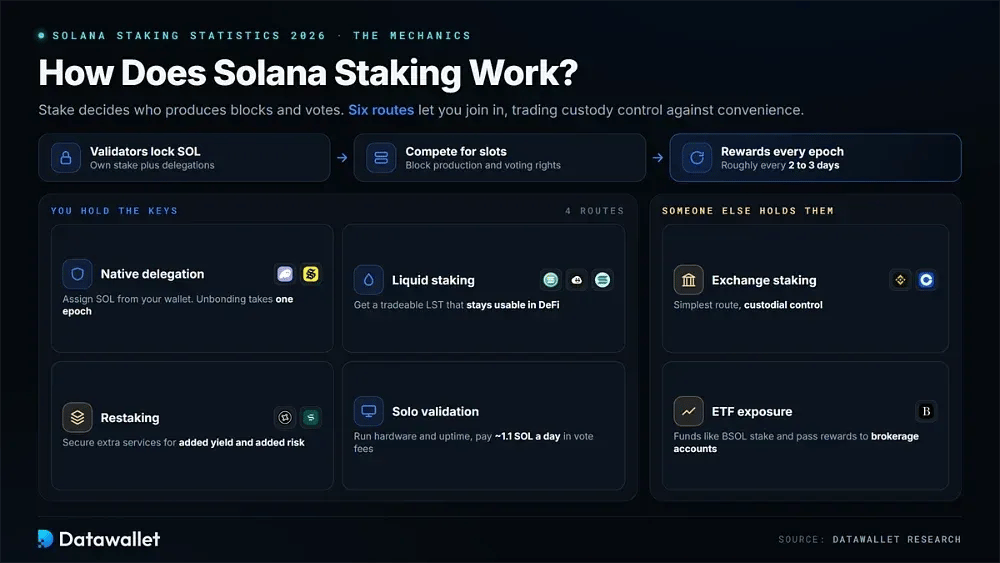
How Does Solana Staking Work?
Solana uses proof-of-stake consensus. Validators lock their own SOL, accept delegated stake, and use that combined stake to compete for block production slots and voting rights. Rewards are distributed to delegators every epoch, which lasts roughly two to three days.
The main ways to stake SOL in 2026:
- Native delegation: Assign SOL directly to a validator from your wallet. The stake account remains under your control, and unbonding takes one full epoch.
- Liquid staking: Deposit SOL with Jito, Sanctum, Marinade, or Jupiter in exchange for a tradeable LST that accumulates rewards while remaining available across DeFi.
- Exchange staking: Services such as Binance or Coinbase select validators on your behalf, offering greater simplicity in exchange for custodial control of your coins.
- Restaking: Place SOL or LSTs into Jito Restaking or Solayer vaults to secure additional services and pursue incremental yield while taking on another layer of risk.
- ETF exposure: Spot products such as BSOL stake their full SOL holdings through designated validators and pass net rewards to shareholders through brokerage accounts.
- Solo validation: Operate your own validator using personal stake and delegations while covering hardware requirements, uptime obligations, and daily voting fees near 1.1 SOL.
How Institutions Stake SOL in 2026
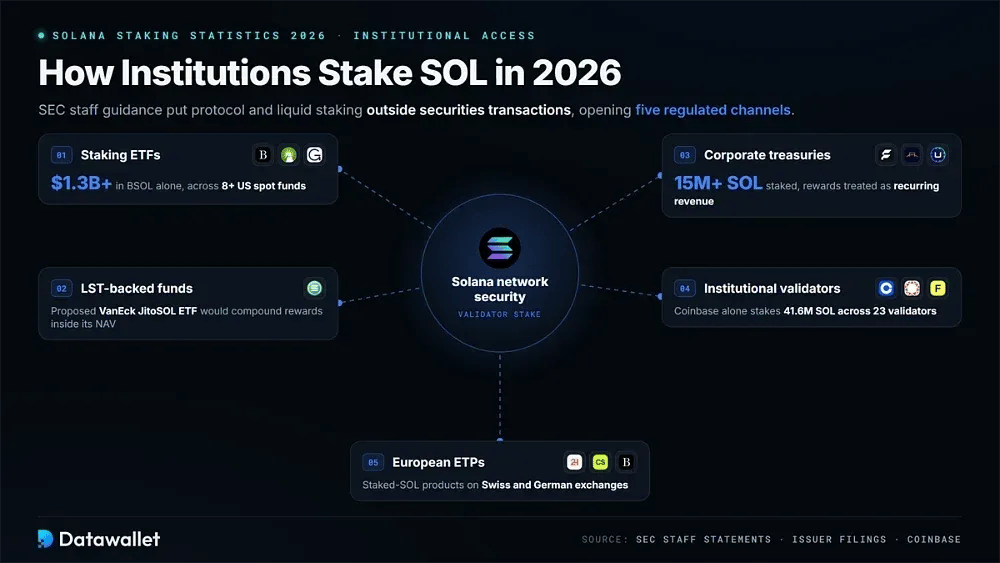
Institutional access to Solana staking changed substantially between 2025 and 2026. SEC staff guidance clarified that protocol staking and liquid staking generally fall outside securities transactions, allowing product structures that direct regulated capital into validators.
The institutional staking stack now spans five distinct channels:
- Staking ETFs: Eight-plus US spot funds stake their holdings through professional validators, with BSOL alone directing more than $1.3 billion of assets into network security.
- LST-backed funds: The proposed VanEck JitoSOL ETF would hold a liquid staking token directly, allowing rewards to compound within its net asset value.
- Corporate treasuries: DAT companies collectively stake more than 15 million SOL and treat validator rewards as recurring revenue that increases their per-share holdings.
- Institutional validators: Coinbase, Helius, Figment, Galaxy, and P2P operate SOC 2-audited infrastructure. Coinbase alone stakes 41.6 million SOL across 23 validators.
- European ETPs: 21Shares, CoinShares, and Bitwise offer staked-SOL products on Swiss and German exchanges, extending yield exposure to brokerage accounts outside the US.
Solana Staking vs. Ethereum Staking
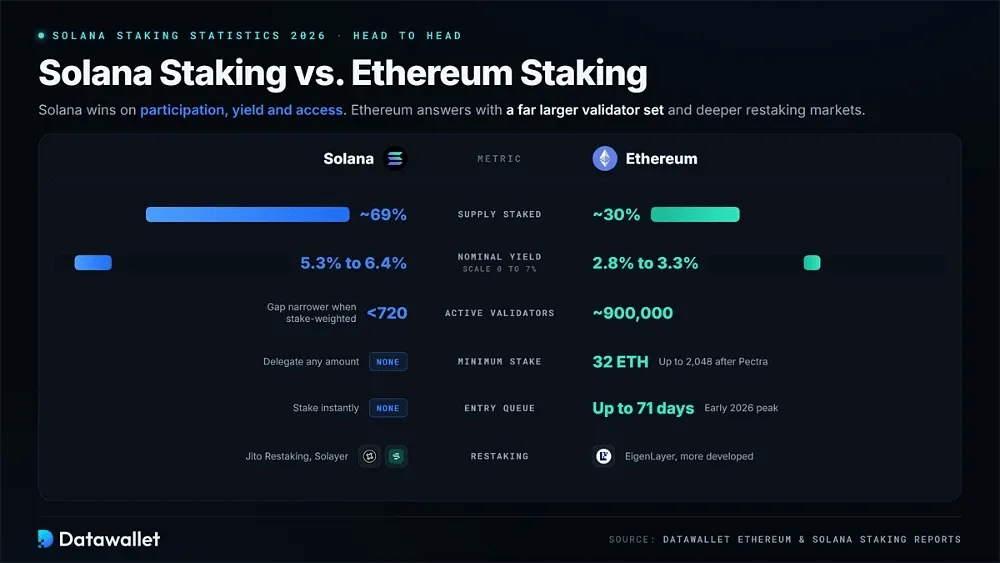
Both Solana and Ethereum rely on proof-of-stake, although their staking models differ considerably. Solana supports delegation with no minimum, has no entry queue, and offers immediate liquidity through LSTs. Ethereum, by contrast, has a much larger validator set and more developed restaking markets.
Around 69% of Solana's supply is staked, far above Ethereum's roughly 30% of supply staked. Nominal Solana yields are also higher at 5.3% to 6.4%, compared with roughly 2.8% to 3.3% on Ethereum. Solana's trade-off is validator concentration: fewer than 720 active validators versus roughly 900,000 on Ethereum, although the difference is considerably narrower when measured by stake-weighted decentralization.
Ethereum validators structurally require 32 ETH, or up to 2,048 following the Pectra upgrade, and must pass through entry queues that reached 71 days in early 2026. Restaking exists on both networks through EigenLayer on Ethereum and Jito Restaking plus Solayer on Solana. Our Ethereum staking statistics report provides the full comparison.
How Much Will You Earn Staking Solana?
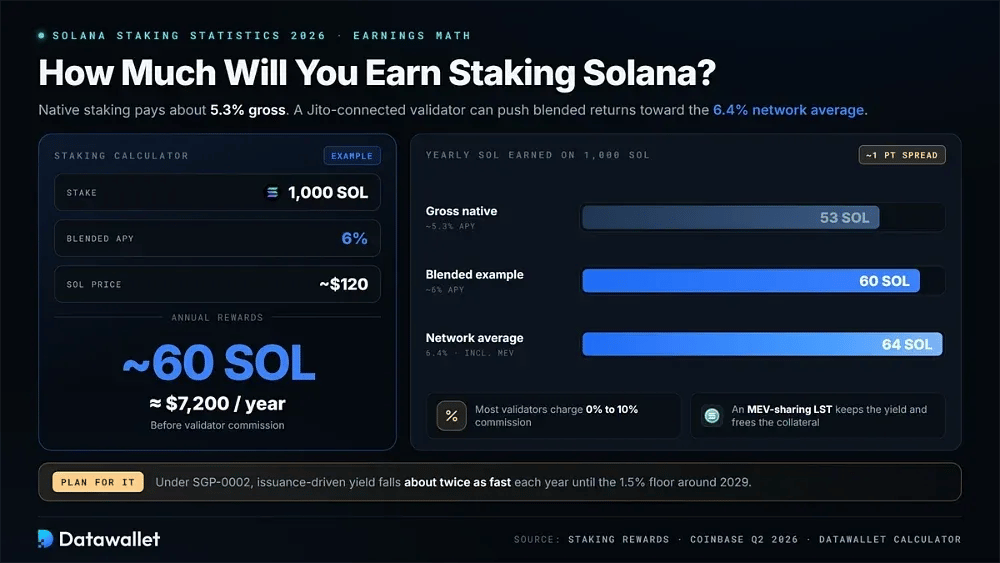
Native Solana staking currently yields about 5.3% gross before commission, with most validators charging between 0% and 10%. MEV tips from a Jito-connected validator can push blended returns toward the 6.4% network average measured by Coinbase during Q2 2026. Validator selection can therefore shift realized yield by a full percentage point.
At a blended 6% APY, staking 1,000 SOL would generate roughly 60 SOL per year before commission. At recent prices near $120, that equals about $7,200. Using an MEV-sharing LST can preserve that yield while keeping the tokens available as collateral, a structure covered in our leveraged staking guide.
You can model different assumptions with our crypto staking calculator. The disinflation path also needs to be included. Following approval of SGP-0002, issuance-driven yield declines roughly twice as quickly each year until the 1.5% terminal rate arrives around 2029, increasing the share of total returns supplied by MEV and priority fees.
Pros and Cons of Solana Staking
Solana combines some of the highest participation-adjusted yields in proof-of-stake with meaningful structural trade-offs. The table summarizes the main factors to consider before delegating SOL.
2026 to 2027 Forecast for Solana Staking
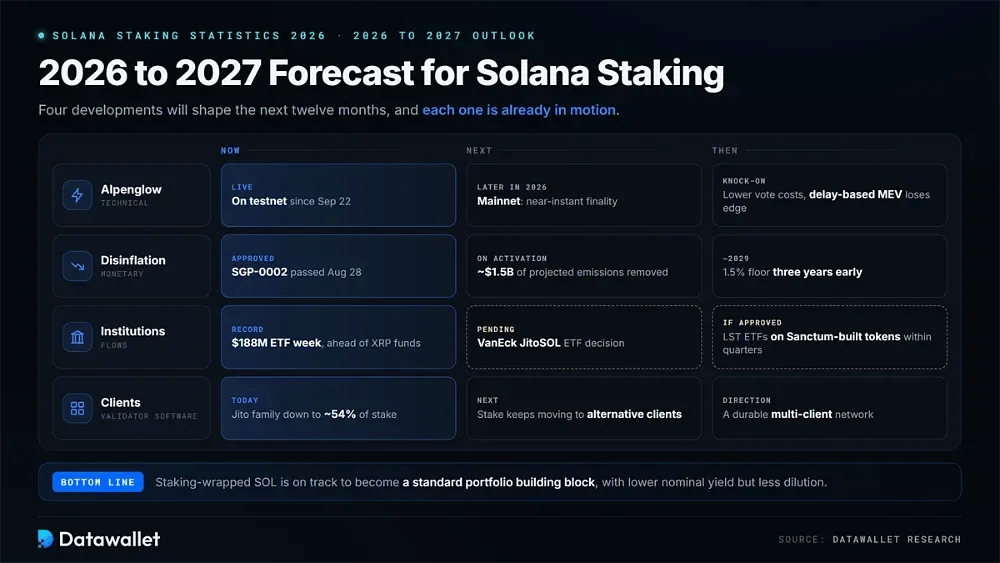
Four developments will shape Solana staking over the next twelve months. Alpenglow still needs to reach mainnet, while the newly approved disinflation schedule changes reward economics. Institutional flows continue to deepen, and the validator ecosystem is moving further into a multi-client structure.
Alpenglow is the largest technical variable. The upgrade is already operating on testnet, with the Foundation targeting mainnet later in 2026. Stakers should expect near-instant finality and substantially lower validator voting costs. MEV economics will also change as delay-based ordering strategies lose some of their advantage.
Monetary policy has already moved onto a steeper path. When SGP-0002 activates, the inflation formula is re-anchored at the switchover slot, removing roughly $1.5 billion in projected future emissions and bringing the terminal rate forward by three years. Stakers receive lower nominal yields in exchange for reduced dilution and a scarcer asset.
Institutional momentum, meanwhile, has continued rather than faded. September's record $188 million ETF week came as Solana products overtook XRP funds in net assets, while the VanEck JitoSOL decision remains pending. Together, those developments point toward staking-wrapped SOL becoming a standard portfolio building block. If regulators approve the first LST-backed ETF, issuers are likely to replicate the model across Sanctum-built tokens within quarters.
Risks of Staking SOL
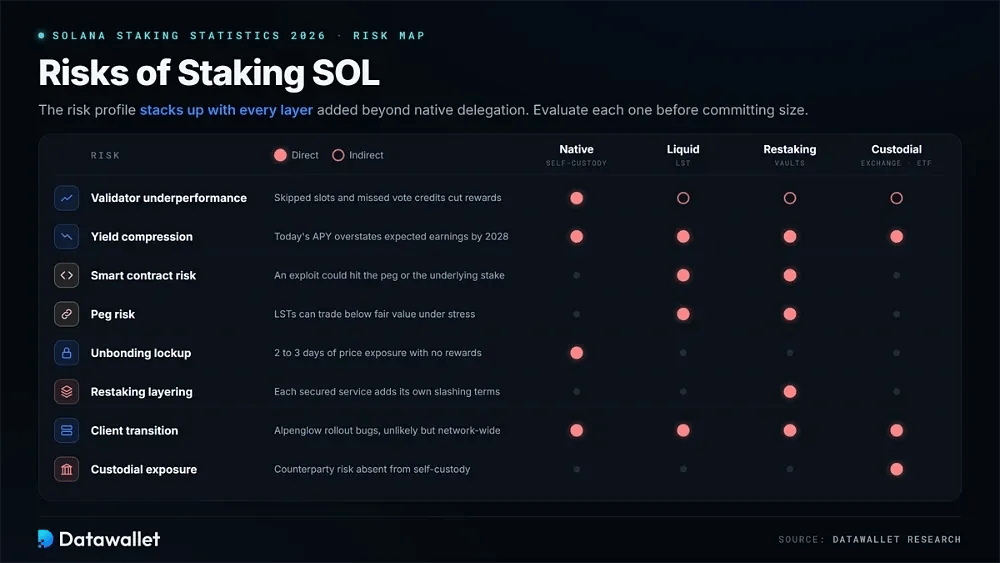
The risk profile expands as a staking position moves beyond native delegation into liquid staking, restaking, or leveraged strategies. Each additional layer should be evaluated separately before committing size.
The main risks to evaluate before staking SOL:
- Validator underperformance: Weak uptime, high skip rates, or missed vote credits reduce rewards directly. Monitor validator performance dashboards and redelegate when necessary.
- Yield compression: The approved double-disinflation schedule materially reduces issuance-based rewards each year, meaning today's headline APY overstates expected earnings by 2028.
- Smart contract risk: LSTs and restaking vaults rely on audited but imperfect code, and an exploit could affect the peg or underlying stake.
- Peg risk: Under liquidity stress, LSTs can trade below their fair value in SOL, requiring sellers either to accept a discount or wait through unbonding.
- Unbonding lockup: Native unstaking requires a full epoch, exposing holders to price movements for roughly two to three days without earning rewards.
- Restaking layering: Restaked assets take on the contract risk of each protocol as well as the slashing conditions attached to every service secured by the stake.
- Client transition risk: The Alpenglow mainnet rollout and broader multi-client migration create upgrade periods in which bugs, though unlikely, could have network-wide effects.
- Custodial exposure: Exchange staking and ETF wrappers introduce counterparty risk that does not exist with self-custodied native delegation.
Final Thoughts
Solana staking in late 2026 is structurally different from where it stood a year earlier. The validator set has become smaller and better capitalized, while meaningful client diversity has ended the Jito monoculture. Solana's first binding onchain governance vote also changed monetary policy. Native delegation still provides the foundation for network security, although most growth is occurring through wrappers.
Those wrappers are attracting significant capital. ETF inflows are approaching $1.6 billion, treasury companies are staking eight-figure SOL positions, and LST issuers are developing institution-specific tokens. Together, these channels have made staking yield Solana's clearest institutional product.
Execution will determine what comes next. Alpenglow still needs a clean mainnet deployment, and the accelerated disinflation schedule will test whether MEV and fees can offset lower issuance. Regulators must also decide whether liquid staking tokens can sit inside ETFs. Stakers positioned across those transitions, rather than anchored to today's APY, will fare best.